Sheet N06 Revision 1 Checked 15 October 2026
Deposit £10 and get 200 free spins with no wagering requirements
£20.00 of face in cycles, £19.20 of average winnings, and £10.00 of the reader’s own money as the price of entry. That last figure is the only one at risk, and it is the one the headline leaves out. Twenty cycles per pound deposited is the rate this package trades at, and the rate is what travels between offers.
20 cycles for each £1 paid in, £2.00 of face per £1
What the conditions leave
Every destination on this spike is bought advertising. The site takes a fee if a reader goes on to register, and no figure printed below moves because of it.
The Spin Sheet
Till receipt No 01
Betportal
Lowest multiple here
For every €1 of spin credit at face per €1
Credit
Debit
No Great Britain licence
Licensed in Anjouan, Comoros, run by BetPortal Gaming Ltd, with Excite Ultra Media Ltd, reference ALSI-202601040-FI2.
Terms read 15 October 2026
Open the offer at Betportal, opens in a new tabThe Spin Sheet
Till receipt No 02
WinBeast
Five staged matches
For every €1 of spin credit at face per €1
Credit
Debit
No Great Britain licence
Licensed in Curaçao, operator not named on the site.
Terms read 15 October 2026
Open the offer at WinBeast, opens in a new tabThe Spin Sheet
Till receipt No 03
EliteSpin
Longest spin window
For every £1 of spin credit at face per £1
Credit
Debit
No Great Britain licence
Licensed in Costa Rica, run by PrimeTier Limited.
Terms read 15 October 2026
Open the offer at EliteSpin, opens in a new tabThe Spin Sheet
Till receipt No 04
Crown Jewelz
Multiple unpublished
No total struck
Credit
Debit
No Great Britain licence
Licensed in Curaçao, number not verified, operator not named on the site.
Terms read 15 October 2026
Open the offer at Crown Jewelz, opens in a new tabThe figure at the foot of a receipt is this site's own arithmetic and nothing an operator has published: the credit, less the share a spin gives back at 96 per cent return to player, less what playing the wagering through costs at the same return. It describes the offer, not one reader's afternoon. Where the conditions price above the credit the receipt prints nothing rather than a negative sum, and where a figure the sum needs is unpublished it prints the condition in the operator's words instead.
Three words stand in the amount column where no figure can. Noted is a published condition that takes value away without leaving the sum a figure to take. Unpriced is a condition whose figure nobody has published, or a credit that is not a sum until a deposit of your own sets it. Own money is money of yours, which is never part of a total.
Not one of the operators printed above holds a Great Britain licence, so the duties that licence carries do not reach them. Every online gambling company licensed in Great Britain has to be part of Gamstop Online, and a reader who has shut themselves out through the scheme is therefore not shut out here. The ceiling of ten times the bonus funds on a wagering requirement, in force since 19 January 2026, is a condition of that licence and binds the companies that hold one. Where a dispute goes instead is a matter for the authority named on the receipt, and the Gambling Commission describes what a reader faces without a British licence as a lack of recourse if things go wrong. Nobody under 18 may hold an account at any of them.
Every term printed on a receipt is the operator's own, and each receipt carries the day it was read. The oldest of those readings is 15 October 2026. What binds a reader is the operator's own full terms, and not a line printed here.
1
Two numbers, and one of them is yours
A package of this shape sets two quantities against each other, and only one of them appears in large type. The large one is a count of cycles. The small one is a sum of the reader’s own money, which has to arrive before any cycle does.
Price the large one first. Two hundred cycles at 10p apiece carry a face of £20.00, and a slot returning 96 per cent gives back 9.6p for each 10p that passes through it. The cycles therefore average £19.20 of winnings, and with no play-through written over them that average is not billed against.
Now the small one. £10.00 goes in, and unlike the cycles it is exposed. It can be lost. It is also, usually, the thing a cashier wants staked at least once, since a deposit withdrawn untouched defeats the object of having asked for it.
Those two facts make the whole sheet. The cycles are the goods and the deposit is the price, and nobody prices goods without writing down what they cost.
Held fixed here:
- Two hundred cycles at 10p, so £20.00 of face.
- A deposit of £10.00.
- A 96 per cent game on both sides of the package.
- No play-through on the cycles, which is what the key says, so the forty times used on this site’s wagered sheets does not enter the arithmetic.
- One pass through a game for the deposit, because a deposit taken straight back out is not a qualifying deposit anywhere. Where a deposit carries a requirement of its own, that is a different structure, and sheet N07 prices it under the key deposit £5 for 100 free spins.
2
The line, run on each side separately
Sheet N06 does its arithmetic with the expression this site uses everywhere:
E = B × (1 – (W × (1 – RTP)) / g)
£19.20 is B on the first run, being what the cycles average. W is the turnover the credit owes, RTP the share a game returns, g the weighting, E the remainder. The two sides go through it one at a time, which is the only honest way to treat a package made of somebody else’s money and your own.
The cycles, with no requirement over them:
E = £19.20 × (1 – 0) = £19.20
The deposit, through a game once:
E = £10.00 × 0.96 = £9.60
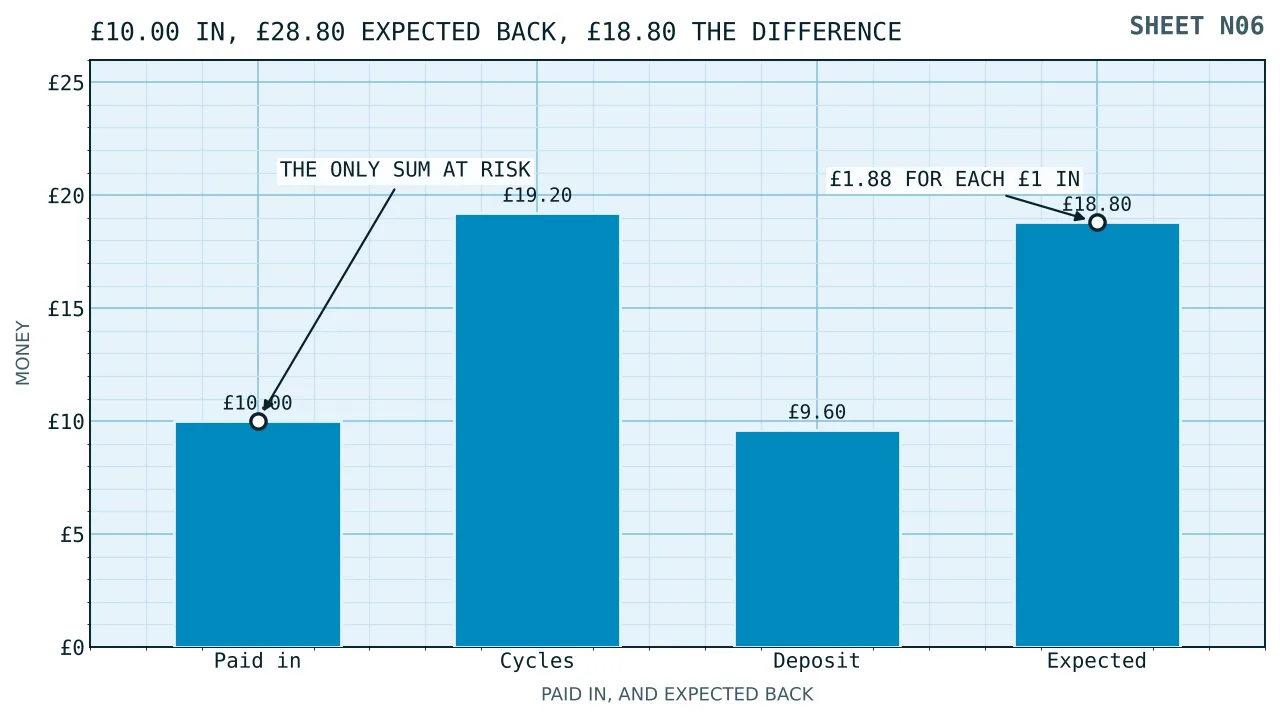
Take both totals together, then set the deposit against them. £19.20 plus £9.60 is £28.80, less the £10.00 that started it, which leaves £18.80 as the expected gain on these assumptions. Divided by the money at risk, that is £1.88 for each pound of the reader’s own.
Two warnings about that figure, because it is the most optimistic number on this sheet. It assumes every cycle is used, that nothing caps the winnings, and that the payment arrives. Each of those assumptions has its own sheet in this section, and each of them subtracts.
3
The rate that outlives the headline
A count of cycles means nothing on its own, because a cashier can print any count it likes by raising the sum it wants first. Divide one by the other and the comparison becomes possible.
| Paid in | Cycles | Cycles per £1 | Face per £1 | Winnings per £1 |
|---|---|---|---|---|
| £5.00 | 100 | 20.0 | £2.00 | £1.92 |
| £10.00 | 200 | 20.0 | £2.00 | £1.92 |
| £10.00 | 100 | 10.0 | £1.00 | £0.96 |
| £20.00 | 300 | 15.0 | £1.50 | £1.44 |
| £25.00 | 500 | 20.0 | £2.00 | £1.92 |
Rows one, two and five are the same package at three sizes. Nothing distinguishes them except how much has to be paid in before it starts, and a reader comparing count against count would rank the last of them first by a factor of five.
Row four looks generous and prices worse than row two. Row three carries the same deposit as row two and half the cycles, which is the comparison the arithmetic was built for.
None of those five is a figure read off anybody’s terms. They are constructed to show what a rate does, and the rate is the thing to carry from one document to the next: cycles divided by pounds paid in, then multiplied by the price of a cycle and by the game’s return.
£1.92 of average winnings per £1 paid in, at 20 cycles to the pound
4
What the tenner buys, in full
Lay the whole thing out as money in and money expected back.
| What it is | Figure |
|---|---|
| Paid in, and at risk | £10.00 |
| Face of the cycles | £20.00 |
| Average winnings from them | £19.20 |
| Deposit after one pass | £9.60 |
| Expected gain | £18.80 |
| Per £1 of your own | £1.88 |
The fifth line is an expectation and not a forecast, and the distinction is sharper here than on a credit-only sheet because real money is on the table. Two hundred cycles at 10p is a short sequence of random events. The commonest single outcome of such a sequence on a slot with large rare prizes is a good deal less than £19.20, and the £10.00 can be gone in its own right.
What the figure does say is what the arrangement is worth repeated. A reader deciding between two packages can compare two such figures honestly. A reader deciding whether tonight will go well cannot use it at all.
5
How long 300 cycles take
Count every cycle the package involves. Two hundred come from the offer, and the deposit at 10p a cycle is another hundred, so the whole arrangement is three hundred game cycles.
Under a British licence their pace has a floor. Between one slot cycle and the next, 2.5 seconds have to elapse before the second may start, which puts three hundred of them at 750 seconds or more. Twelve minutes and thirty seconds, as a minimum rather than an expectation.
Nor can automation get round it. Each game cycle needs a separate commitment from the customer under RTS 8A, whose guidance makes one narrow exception, and that exception is poker. Three hundred cycles is three hundred deliberate acts.
Neither rule appears offshore. Curaçao’s policy for licensed operators sets no minimum interval and leaves autoplay alone, so the same three hundred cycles take whatever time the software needs.
Why this matters on a deposit-linked package rather than a credit-only one: the deposit is real money and the pace decides how long the player sits in front of a decision about whether to pay in again. Twelve and a half minutes is not a long time. It is, though, two hundred and ninety-nine more opportunities to stop than an automated sequence would have given.
6
What a first deposit sets off
Paying in for the first time starts a set of British obligations that have nothing to do with the bonus and everything to do with the money. Each of them is easier to judge with £10.00 standing next to it.
A limit, put first and declined only on purpose
Setting a financial limit is the default choice under the live standard, not an option buried in an account menu. The prompt arrives either during registration or at the moment of that first payment, turning it down takes a deliberate act by the customer, and confirmation of the refusal has to be in hand before any money is deposited or staked. Whatever figure is chosen must be applied as quickly as is practicable, and the player has to learn when it starts to bind.
The shape it has to take
The figure is typed in rather than picked off a short menu, which matters when the sum a reader has in mind is £10.00 and the menu starts at twenty. Limits bind at account level at minimum. Among the periods offered there must be one day, seven days and one month. Only a facility capping what goes into an account over a period may be described as a deposit limit, and limits of that kind get at least the prominence of any other sort.
Two limits at once, and the arithmetic of the tighter one
Where two periods overlap, the stricter governs, and the Commission publishes a worked case. Put a ceiling of £10 on a day alongside one of £100 on a week and what the system must permit is £10 daily and £70 weekly, because seven tens come to seventy and the tighter figure wins. Deposits then stop until the period turns over or the customer acts to raise the limit, an act that carries a standard day of cooling off before it takes effect.
Note what that does to a package pitched at £10.00. A daily ceiling at the same figure makes the qualifying deposit exactly one payment a day, and a weekly ceiling of £70.00 makes it seven.
A threshold fifteen payments away
Light-touch financial vulnerability checks begin above a monthly net deposit threshold. The figure has stood at £150 a month since 28 February 2025, down from £500, where it began on 30 August 2024. At £10.00 a payment, fifteen of them reach it. The separate enhanced assessments are still a pilot, are not live, and the Commission says neither they nor the light-touch checks touch a credit rating.
7
The rules built around paying in
Offers of this shape frequently come from operators with no Great Britain licence, and everything in part 6 then falls away along with what follows.
How the money may arrive
Since 14 April 2020 a £10.00 deposit at a British licensee cannot be made on a credit card, and routing that card through a money service business does not put the payment outside the condition. Every remote licence is within its scope.
What may be bundled with what
One incentive, one kind of gambling product, from 19 January 2026. Cycles alongside casino credit stay inside a single type, a slot being a casino product. Cycles alongside bingo tickets reach across two and are caught. Three carve-outs sit against what a reader would guess: two products of one type are untouched, a raffle with a scratchcard being the published example; one email may carry separate casino and betting offers where the customer has opted into marketing for both; and credit that the customer may spend on whichever product they like falls outside the ban entirely.
What a ten-times ceiling would mean here
The same date capped a wagering requirement at ten times the bonus money. Had the cycles on this package carried one at that ceiling, the £19.20 they average would owe £192.00 of staking, costing £7.68 and leaving £11.52. So the absence of a requirement is worth £7.68 measured against the strictest requirement a British licence permits, and more than that against anything looser.
What Curaçao puts in its place
Bonuses there get two sentences, asking for transparent and clear terms and for promotion that is not aggressive enough to encourage excessive gambling. Nothing caps a multiple. Nothing bars one incentive holding several product types. There is no credit card rule and none of the prompt obligations in part 6. Deposit limits are required, running daily, weekly or monthly, with a reduction effective at once and an increase waiting seven days, which is longer than Britain asks and deserves saying.
8
Pricing a qualifying deposit
Five lines. The first is the one the headline wants you to skip.
| The step | This package |
|---|---|
| Write down what you pay in | £10.00 |
| Count the cycles, then price one | 200 cycles, 10p each |
| Put the game’s return through them | £19.20 |
| Divide cycles by pounds paid in | 20.0 per £1 |
| Net, after the deposit’s own pass | £18.80 |
The fourth line is the portable one. It survives a change of spin price, a change of game and a change of cashier, and it is the only figure that lets two packages of different sizes be compared at all.
Three things still to subtract, each with its own sheet. Sheet N01, keyed 50 free spins no deposit no wager, costs out the cap that sits over what the cycles may win. Sheet N02, keyed 70 free spins no deposit no wager, handles instalments and the clock set over them. Sheet N07, keyed deposit £5 for 100 free spins, covers a requirement that has slid off the cycles and onto the deposit. All three are listed under Nothing asked back.
Questions
- What does a £10 deposit with 200 free spins actually return?
- £18.80 expected, on these assumptions. Two hundred cycles at 10p put £20.00 of face on the sheet, £19.20 is what comes back on average where a game returns 96 per cent, and no play-through is billed against either figure. The £10.00 paid in comes back as £9.60 after a single pass through a game. Add those and subtract the deposit, and the expected gain is £18.80, or £1.88 for each pound of your own.
- Which part of this package is actually at risk?
- Only the deposit. The cycles are a credit: nothing of the reader’s own stands behind them, so the worst they can do is return nothing. The £10.00 is different. It is real money, it is normally expected to pass through a game at least once, and a deposit taken straight back out untouched is not a qualifying deposit anywhere.
- How do I compare two packages with different deposits?
- Divide the cycles by the pounds paid in. Two hundred cycles for £10.00 and a hundred for £5.00 are the same arrangement at two sizes, both running at twenty cycles to the pound. A package offering a hundred cycles for £10.00 runs at ten to the pound and is half the offer, though its headline count looks the same as the smaller one.
- Why does the price of one cycle matter so much?
- Because it converts a count into money and nothing else does. At 10p a cycle the pound buys twenty of them, so £2.00 of face rides on each pound paid in, and a 96 per cent return leaves £1.92 of it as the average take. Halve the cycle price and both figures halve. No published rule in Britain fixes what a cycle is worth, so the figure has to be read off the terms.
- How long does a package like this take to use?
- At least twelve and a half minutes under a British licence. Two hundred cycles come from the offer and another hundred from a £10.00 deposit at 10p, which is three hundred in all, and 2.5 seconds is the shortest interval allowed between one slot cycle opening and the next. That makes 750 seconds, with each cycle needing its own commitment from the player.
- What happens when I make my first deposit at a licensed site?
- A financial limit is put to you as the default choice, either during registration or at that first payment, and declining takes a positive act with confirmation received first. Durations have to reach a month, a week and a day; the sum is typed in rather than picked off a short menu; and the ceiling binds across the whole account at the very least.
- What happens if I set a daily limit and a weekly one together?
- The tighter one binds, and the Commission publishes the arithmetic. Put £100 a week beside £10 a day and seven days of the smaller ceiling is all that passes, so the week yields £70 and not the £100 the weekly figure appears to promise. Once a limit is reached, deposits stop until the period restarts or the customer acts to raise it, which carries a standard day of cooling off.
- What is lost when the package has no British licence?
- Everything in parts 6 and 7. No prompt to set a financial limit, no default limit, no free text box, no required durations, no credit card ban, no ban on mixing gambling product types in one incentive, no ten-times ceiling on a requirement, no 2.5-second floor under the pace, and no place in Gamstop Online. Curaçao does require daily, weekly or monthly deposit limits, with an increase waiting seven days against a British minimum of one.